
Robinhood Built a Blockchain for Stocks. The Cat Memecoins Took It Over.
$13 million in tokenised equities, memecoins worth ten times that: what Robinhood Chain is, why CASHCAT flooded it, and how investors actually get access.




Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.
Updated 1 October 2026: the gas subsidy lapsed on 29 September. The first reading since is split: chain fees are down roughly 31 percent week on week and Pons launchpad fees roughly 43 percent, while value locked holds above the billion-dollar mark at around $1.03 billion. Plus new figures for DEX volume and CASHCAT (as of 1 October). The earlier sections on the 6 August Robinhood listing and on the July, August and September sequence remain as a record.
Robinhood brought its own blockchain online this summer so that European customers could trade American stocks around the clock. Six weeks later more than 420,000 wallets hold tokenised assets on the chain — and the largest cat memecoin on it was still briefly worth more than the tokenised equities combined. On 6 August, Robinhood took that very memecoin into its own app.
You can dismiss that as a curiosity. The more useful question is why it happened, because the pattern has repeated on every new chain for years. This guide explains what Robinhood Chain technically is, how the memecoin wave came about, how investors get access, and what to watch for.
What Robinhood Chain technically is
The public mainnet went live on 1 July 2026. Technically it is an Ethereum layer-2 built on the Arbitrum Orbit stack: security comes from Ethereum, transaction fees are paid in ETH, and execution runs on a dedicated chain operated by Robinhood. Arbitrum documented the launch itself.
The purpose was known from the outset: tokenised stocks and ETFs. Robinhood began issuing more than 200 US stock and ETF tokens to EU customers in 2025, initially on Arbitrum One, intending to migrate them to its own chain later. The appeal for European investors is straightforward — trading well beyond US market hours, dividends handled, and a security that can be moved technically like a token.
The numbers after thirteen weeks
| Metric | Value |
|---|---|
| Mainnet launch | 1 July 2026 |
| Total value locked | around $1.03 billion on 1 October — the billion-dollar mark holding even after the gas subsidy ended (DefiLlama, as of 1 October). For the sequence: around $1.00 billion on 24 September; on Blockchain.News's count it was crossed on 22 September; around $929 million on 17 September, around $536 million on 17 August (The Coin Republic, 18 August), up more than 45 percent month to date (The Block, 17 August). Other providers put it near $775 million in early August. The spread is real, not rounding — the providers count different things. |
| Daily transactions (average) | around 7.6 million in early September (crypto.news, 4 September); 11.6 million in the week of 3–9 August, about 30 percent above the prior week |
| Wallets holding tokenised assets (RWAs) | more than 420,000 after six weeks (as of early August) |
| Value of tokenised assets (RWAs) | around $32 million on the narrow measure, up 120 percent month over month. Their share of value locked fell from nearly a third on 7 July to 6 percent in mid-August. DeFiLlama, counting more broadly, shows $124.8 million. |
| Stablecoins on the chain | around $640 million, up more than 22 percent month to date. USDG accounts for $350.8 million (54.8 percent) and USDe for $287.7 million — up roughly 167 percent over 30 days. |
| DEX volume | around $1.51 billion in 24 hours, $9.42 billion over seven days and $56.0 billion over 30 days on 1 October, roughly $98.9 billion cumulative since launch (DefiLlama, as of 1 October); the seven-day figure sits about 11 percent below the prior week. On 24 September it was $10.5 billion over seven days and $54.3 billion over 30 days, and on 17 September $1.54 billion in 24 hours and $39.1 billion over 30 days. On 13 September it was $1.88 billion in a single day, which Bloomingbit counts as more than half of Uniswap's entire volume. For comparison: around $878 million on 12 July, $500–700 million in early August |
| Chain fees | around $5.8 million in 24 hours, $35.1 million over seven days and $351.8 million over 30 days, roughly $712.7 million all time (as of 1 October, DefiLlama); week on week that is about 31 percent less. On 24 September it was $6.6 million in 24 hours and $48.6 million over seven days, and on 17 September $7.8 million in 24 hours and $303.6 million over 30 days. On 2 September the chain took in $4.01 million while Solana took in $81,714 the same day (crypto.news, 4 September). |
| Pons launchpad | around $1.6 million in fees over 24 hours, $11.2 million over seven days, $137.1 million over 30 days and $184.9 million all time, V1 and V2 combined (as of 1 October, DefiLlama). Against $19.5 million over seven days on 24 September, weekly fees are down roughly 43 percent, and against $35.0 million on 17 September roughly 68 percent. Roughly 25,000 tokens were issued through it on 2 September alone (Bloomingbit, 14 September). |
| Gas subsidy | 90 days from mainnet launch, lapsed on 29 September (crypto.news). Since then every transaction from the Robinhood Wallet pays gas in ETH again; until then it was free. |
| CASHCAT: all-time high / 1 October | around $0.3143 (3 September, the all-time high) / around $0.1699, market capitalisation about $168 million, leaving it roughly 46 percent below the high and about 7 percent higher on the week (CoinGecko, as of 1 October) |
The finding for the second half of August read as follows: In absolute terms tokenised assets are growing: around $32 million on the narrow measure, up 120 percent month over month, held across more than 420,000 wallets, with Nvidia and Apple among the most-held positions. Everything else is simply growing faster. Their share of value locked fell from nearly a third on 7 July to six percent, while stablecoins on the chain climbed to roughly $640 million (The Block, 17 August). The growth is therefore not coming from the product the chain was built for but from parked dollar balances, USDe above all. It fits that active addresses sit eleven percent below the 16 July peak while transaction counts set records: it is not more people trading, it is the same people trading more often. For a chain that justifies itself through adoption, that is the less comfortable of the two readings.
The CASHCAT case
Attention was triggered by a token called CASHCAT. It launched days after mainnet, has a fixed supply of one billion units, no product, no revenue and no named team. The name alludes to a company name discarded in 2010: Vlad Tenev and Baiju Bhatt first intended to call their startup "CashCat" before settling on Robinhood.
Robinhood did not issue, commission or endorse the token, and the project's own site explicitly denies any connection to the company — it describes itself as fan fiction with a ticker. Since 6 August 2026, however, CASHCAT is tradable in the Robinhood app. Why that is something other than an endorsement is set out below; it is the single most important distinction in this article.
The sequence:
- In the first 24 hours the price rose by more than 1,700 percent.
- Over the first week it was more than 2,100 percent. The peak valuation on 8 July was around $156 million. Some data providers show above $220 million for 12 July — that the sources diverge this far says a good deal about data quality in this segment.
- On 13 July the token lost over 30 percent after the Noxa launchpad ceased operations.
- In early August CASHCAT traded at roughly $0.08 to $0.09, about 60 percent below the high, with large addresses continuing to accumulate.
- On 6 August, Robinhood opened the token for spot trading in its own US app. The price rose around 90 percent within 24 hours to $0.1483, volume climbed more than 250 percent to $109 million, and the valuation passed $150 million (Cryptonews).
- The timing of some positions stood out: several wallets went long hours before the announcement. That does not establish insider trading — it does call for an explanation.
- On 3 September CASHCAT set a new all-time high at around $0.3143, replacing the 11 July mark. On 17 September it trades near $0.1912 at a market capitalisation of about $189 million, on daily volume of roughly $21.9 million. That is a gain of some 82 percent over 30 days and a drawdown of roughly 39 percent from the high (CoinGecko, retrieved 17 September). Both numbers stand side by side, and that is the point. By 24 September the price had eased further to around $0.1597 at a market capitalisation of about $158 million. On 1 October CASHCAT trades near $0.1699 at a market capitalisation of about $168 million, on daily volume of roughly $15.0 million; that is roughly 46 percent below the all-time high, about 7 percent higher on the week and about 27 percent lower over 30 days (CoinGecko, as of 1 October). That the token gained in the same week chain fees fell 31 percent shows how little a memecoin price has to do with activity on the chain beneath it.
- For the record: on 20 August CASHCAT traded near $0.121 at a market capitalisation of about $119 million, down some 26 percent on the week (CoinGecko). That leaves it just under 47 percent below the all-time high of around $0.2288 set on 11 July. The Robinhood listing carried the price briefly; it did not turn it.
The trading pool is considerably smaller than the market capitalisation suggests. At peak, some $98 million of daily volume ran through this single token, around 17 percent of the chain's entire DEX volume. Cash Dog and Hoodrat followed the same pattern alongside it.
September: bigger numbers, and a deadline
The picture shifted again in September, and in both directions at once. Value locked has now reached the billion mark: around $1.00 billion on 24 September (DefiLlama), crossed on 22 September on Blockchain.News's count. DEX volume reached $1.88 billion in a single day on 13 September (Bloomingbit, 14 September). At the same time it has become clearer where the activity comes from: most of the fee-generating usage runs through the memecoin launchpad Pons and through trading bots, not through the tokenised equities (crypto.news, 4 September). On 2 September the chain took in $4.01 million in revenue while Solana took in $81,714. Anyone reading that as Robinhood Chain overtaking Solana is comparing a subsidised launch phase with a settled network.
The free gas stopped on 29 September: chain fees fall 31 percent
That subsidy had an expiry date, and it has arrived. A 90-day gas rebate for transactions from the Robinhood Wallet began with the mainnet launch on 1 July; it lapsed on 29 September (crypto.news). Until then a swap there cost no network fee; since then every transaction pays in ETH again. A launchpad minting 25,000 tokens in a day depends on a very low cost per attempt — for investors this was less a price question than a liquidity question.
The answer comes in two parts. Chain fees stand at around $35.1 million over seven days, roughly 31 percent below the prior week; at Pons they have fallen from around $19.5 million to around $11.2 million, down roughly 43 percent. DEX volume gave up less ground: around $9.42 billion over seven days, about 11 percent below the prior week. Value locked, at around $1.03 billion, is in fact slightly above its 24 September level (DefiLlama, as of 1 October).
For investors that means the capital is staying put for now, but the fast turnover on top of it is not. Anyone trading memecoins on this chain has met thinner pools since 29 September and pays gas on top — two costs that compound on small positions. Whether the decline becomes a floor or the start of an exodus will only show over the coming weeks; it cannot be predicted.

Why memecoins and not the stock tokens?
The obvious explanation — that investors are irrational — falls short. There are four structural reasons, and they appear on new chains in the same order every time.
1. Regulation takes time; a memecoin does not
A tokenised Apple share is a regulated financial instrument. It requires an issuer, a custodian, prospectus obligations, KYC and authorisation in each jurisdiction. A cat token requires a wallet and a few minutes. On a new chain, the first visible activity is therefore almost always the unregulated kind.
One signal is already visible ahead of the deadline: fees at the Pons launchpad have fallen from around $35.0 million to around $19.5 million week on week (DefiLlama, retrieved 24 September), and the chain's DEX volume over those same seven days sits about 20 percent below the prior week. Value locked keeps climbing, in other words, while the trading that produces the fees is already easing. What expires on 29 September therefore meets an already quieter chain.
New: memecoins with real assets behind them
Since mid-September, part of the ecosystem has been answering the pure-speculation charge with a construction of its own. The Tesoro project launched the TORO token on Robinhood Chain, where a three percent tax on every trade buys tokenised gold and tokenised equities and moves them into a shared holding (Forbes, 18 September; Traders Union). On this chain that closes a circle: the tokenised equities it was built for are arriving by way of the memecoins that took it over.
For investors it changes less than it sounds. A backing pot is not a price floor: it guarantees no minimum value, it is not enforceable, and whether the cover bought matches what a project claims can only be checked on-chain. What a three percent tax reliably does do is make every purchase and every sale more expensive. The pattern is new; the yardstick is the same as for any other token on this chain.
 FOMO FamilySponsored
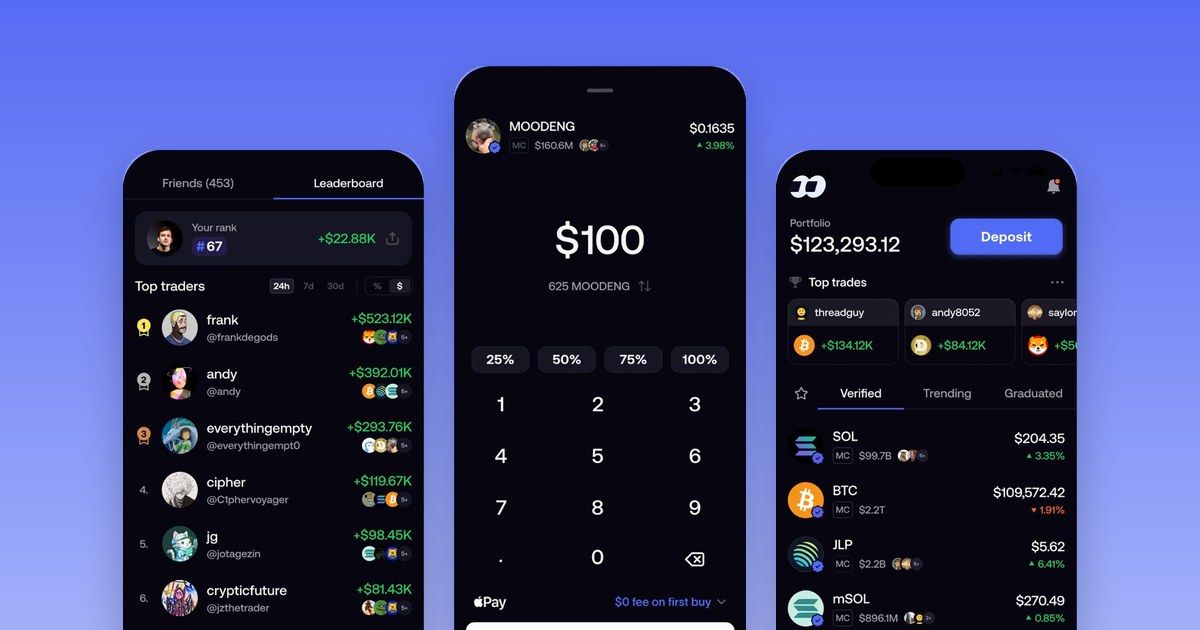
Buy meme tokens straight from your phone
We used FOMO Family ourselves and bought meme tokens with it, Robinhood Chain included. Deposit, find the token, buy: it takes seconds. Our link gets you ten percent off the fees.
Get the app and 10% off fees →Memecoins are high risk, a total loss is possible. Partner link.
2. Thin markets move sharply
When only a few million sit in the pool, even small buys trigger triple-digit percentage moves. Those moves produce screenshots, screenshots attract new buyers, and the inflow produces the next move. This is not specific to Robinhood Chain; it applies to any thin market.
3. The brand name is mistaken for vetting
"Robinhood Chain" sounds like Robinhood. The company operates the chain but neither vets nor stands behind any token on it, no more than Ethereum is liable for tokens on Ethereum. That confusion is likely a substantial part of the inflow, and it costs people money regularly.
Since 6 August this point needs more explaining, because Robinhood has now actually opened CASHCAT for trading. A listing is a decision about what a broker offers its customers — it is not a statement that a token has a team, a product or a future. The same app has carried Dogecoin for years without anyone reading that as a quality check. Nothing about the token itself has changed: no product, no revenue, anonymous developers, and a project site that still denies any connection to the company. The fallacy this section is about has not been refuted by the listing. It has only become more expensive, because it now sounds more plausible.
4. The stock tokens are too unexciting for this audience
If you can already invest inside the Robinhood app, there is little reason to set up a wallet, bridge funds and pay gas in ETH. The added value of tokenisation — longer trading hours and combination with DeFi applications — only arrives once such products exist. So far they do not.
Getting access
Two entirely different routes are routinely confused here.
The stock tokens run through Robinhood itself and are available to EU customers within that product. This is a regulated route with an account, identity verification and tax reporting.
The memecoins run on the chain and belong to nobody. The route involves an EVM wallet, adding Robinhood Chain as a network, ETH for gas and a swap on a DEX on the chain. There is no support, no reversal and no counterparty. With the wrong contract address the money is gone, and nobody is responsible.
This is also where the difference between watching and trading becomes obvious: Dexscreener and TradingView give you charts, not execution. One mobile alternative is the trading app FOMO Family, which lets you discover, swipe through and trade meme and low-cap tokens directly in the app, with a fast deposit flow. Download the app through the link and you get ten percent off trading fees. There is also community speculation about a possible airdrop for active users — that is unconfirmed, the provider has promised nothing, and it is not a reason to deposit money. None of this changes the risk: meme and low-cap trading stays highly volatile, and losing the entire position is possible at any time.
Four checks before buying
- Verify the contract address against two independent sources. Do not take it from a Telegram post. Clones with identical names and logos are common on new chains.
- Look at liquidity rather than market capitalisation. What matters is how much sits in the pool and whether it is locked. At a $90 million valuation with $4 million of pool liquidity, exiting at the quoted price is effectively impossible.
- Check holder distribution. If 40 percent of supply sits on ten addresses, you are helping to fund their exit.
- Size the position as a total loss. The question is not how much you want to make, but what amount you could write off entirely without it changing your plans.
The tax side
Rules differ by jurisdiction, and European readers should take care here. In Germany, memecoin gains fall under private disposals (§ 23 EStG): sold within a year they are taxed at your personal income tax rate, and only a total annual gain below €1,000 stays tax-free; it is a threshold rather than an allowance, so a gain of €1,000 or more makes the entire gain taxable. In the UK and most other markets, capital gains rules apply from the first disposal.
Correction (September 29, 2026): An earlier version said that only a gain above €1,000 makes the entire gain taxable. Under § 23(3) sentence 5 of the German Income Tax Act, the total gain from private disposals is only tax-free if it is less than €1,000 in the calendar year; from €1,000 the entire gain is taxable.
The more relevant point in practice is the same everywhere: every token-to-token swap is a taxable event. Thirty swaps across an active weekend on a DEX mean thirty disposals to document, on a chain many tax tools do not yet recognise. It is worth exporting your transaction history early, while the addresses can still be attributed. Which tools handle exotic chains is covered in our crypto tax software comparison.
Three things to measure the project by
- Does stock-token volume actually move onto the chain? By mid-August the answer got clearer and less flattering: tokenised assets are growing in absolute terms, but their share of value locked has fallen from nearly a third to six percent. More than 420,000 wallets hold such positions — their weight on the chain has shrunk, not grown. That does not pass the test.
- Do applications emerge that use the stock tokens? Lending against tokenised equities, hedging strategies, automated portfolios — only that justifies the detour through a blockchain.
- Does memecoin activity survive the loss of infrastructure? The Noxa shutdown on 13 July showed how quickly the foundation under these tokens can disappear. The next and much larger test comes at the end of September, when the 90-day gas subsidy lapses (crypto.news, 4 September). From 29 September this point becomes measurable rather than merely arguable.
Robinhood Chain: What to take away
Robinhood Chain is the most serious attempt yet by a large broker to move equities onto its own blockchain. At the same time, this summer shows that infrastructure cannot dictate what it gets used for. Since 29 September the chain has carried its traffic without a subsidy, and the first reading is this: the capital stays, the turnover shrinks.
For investors, one distinction matters more than any price forecast:
- The stock tokens are a regulated product with a legible use case and an open adoption question. Whether you need them is debatable, but they do not carry the risk of losing everything overnight.
- The memecoins on top are a zero-sum game. Early buyers' gains come out of later buyers' losses. That is not a moral judgement but arithmetic. CASHCAT falling 60 percent below its high in July, rising around 90 percent after the August Robinhood listing, setting a new all-time high near $0.3143 on 3 September and trading roughly 46 percent below it four weeks later is the norm in this segment, not the exception.
Anyone who blends the two because both say "Robinhood" is missing the most important difference.
In practical terms: decide what share of your crypto holdings you deliberately allocate to speculation. Experience suggests a single-digit percentage is sustainable. The rest belongs in a savings plan into the large caps and on a hardware wallet. What that looks like in practice: our guide to buying bitcoin and the hardware wallet comparison.
One conclusion outlives this summer: a memecoin season is not a market cycle but a sentiment indicator. It shows where liquidity is looking for quick moves, not where long-term value is being created.
Disclosure: some of the providers named in this article work with us through partner programmes. This has no influence on our editorial assessment.
(As of 1 October 2026. This article is not investment advice. Prices and fee structures change; check the terms with the provider before you buy. Memecoins can lose their entire value; invest only amounts whose total loss you can absorb.)
Frequently asked questions about Robinhood Chain
Transparency note: This article was produced with the assistance of artificial intelligence and reviewed by our editorial team before publication. All figures and claims were checked against the primary sources linked in the text. The feature image was generated with AI.
Related articles
- Robinhood Chain: The Free Gas Ends in Late September - the Stress Test for Its Memecoins
- Robinhood Chain After September 29: What the End of Free Gas Changes for the Stock Chain
- DTCC Tokenized Securities: Is Wall Street About to Bring Stocks On-Chain?
- Arbitrum Up 150 Percent In A Month: Is Robinhood Carrying The Price?
- Selling Memecoins: These Tax Rules Apply in Germany as of 2026
Which topics should we dive deeper into?
Select what genuinely interests you. Your picks feed directly into our editorial planning.
Crypto news that's actually worth your time.
Weekly. 60 seconds. Carefully curated by our editors: no hype, no promo flood, no spam.

January 5, 2026 5:39 PM
Top 10 Memecoins That Exploded at the Start of 2026: Where They Stand Now
In the first week of 2026 PEPE, BONK, FLOKI and seven other tokens posted weekly gains of 34 to 68%. By late September most of them trade well below their early-January level.
July 11, 2026 6:49 PM
Crypto Price Today: Bitcoin Holds $64K as Robinhood Lets AI Bots Trade Crypto
The market is green again as BTC clings to a key level — but the bigger shift is that AI bots may soon be placing your trades for you. Here's today's snapshot.
September 10, 2026 9:01 AM
Hunter Biden's $LAPTOP Memecoin Crashed 98% Within Minutes Of Launch
$LAPTOP was pitched as payback for traders burned by $TRUMP. It lost almost everything before most claimants finished reading the airdrop page.
June 1, 2026 1:17 PM
Binance Launches US Stock Trading with Upcoming bStocks Tokenization on BNB Chain
Binance has introduced zero-commission US stock and ETF trading for non-US users, with plans to launch tokenized on-chain equities via bStocks.
January 13, 2026 10:11 AM

PEPE Was Up 50% in Early 2026: Did PEPE Coin Break the Descending Triangle?
PEPE gained about 50% in the first days of 2026 and pressed against a descending triangle. It broke lower instead: the support at $0.0000040 gave way and PEPE fell to about $0.0000023 in July.

September 22, 2026 1:15 AM
Memecoin Rally: Why Memecoins Are Rising and What to Check Before You Buy
The memecoin sector stands 9.01 percent higher, the overall market only 2.90 percent. The arithmetic behind it shows that two tokens carry three quarters of the move and that the sector has no occasion of its own.
September 2, 2026 10:30 AM
Tokenized Stocks: Who Owns the Share When the Register Sits on a Blockchain
The US Securities and Exchange Commission wants to allow the official share register to be kept on a blockchain. What the proposal of September 1, 2026 means for tokenized stocks and for your ownership.
August 20, 2024 3:00 PM

New US Senate Proposal Submitted For Crypto Tax Exemption
The US Senate has recently submitted a new proposal to exempt crypto transactions from federal taxes. Here are more details of this submission, and a list of exempted countries it could be joining...
May 22, 2025 11:00 PM
You Can Now Trade Tesla and Apple on Kraken... Here's How
Crypto exchange Kraken is launching tokenized stocks for Tesla, Apple, and Nvidia—giving non-U.S. users 24/7 access to some of the world’s biggest companies.
May 15, 2026 9:47 AM
Top 10 Altcoins to Buy in May 2026 as Bitcoin Recovers
Here are the top 10 altcoins to buy in May 2026 as Bitcoin rebounds near $80K and market momentum shifts.
September 28, 2026 7:17 PM
Polygon 2026: Polymarket Takes 84 Percent of the Fees With It to Its Own Chain
Polygon holds $765 million, and 83.6 percent of its fees come from a single protocol that has announced a move to its own chain. What is left of the ecosystem afterwards, what POL is still worth and what holders in Germany should watch.
August 17, 2026 6:18 AM
Robinhood Chain NFTs: How StonkBrokers Turned a JPEG Into a Brokerage Account
An NFT collection on Robinhood Chain now has a higher floor price than Bored Ape Yacht Club. It has 630 owners. And its price is not really a price at all - it is a formula.

August 9, 2024 11:13 AM
Franklin Templeton Launches Blockchain Fund on Arbitrum
Franklin Templeton has just launched a new blockchain fund on the Arbitrum network. Find out what this means for Arbitrum and the future of investing.

October 2, 2023 5:39 AM
Chainlink Collaborates with ANZ Bank: A Glimpse into Cross-Chain Tech’s Future
Explore Chainlink's strategic alliance with ANZ, a banking powerhouse with over $670 billion in assets. Uncover the potential of the Cross-Chain Interoperability Protocol in revolutionizing tokenized assets.
April 10, 2023 1:33 PM
Comparing Ethereum’s Layer 2 Solutions: A Look at zkSync, Arbitrum, and Optimism
Learn about the advantages and disadvantages of zkSync, Arbitrum, and Optimism - three of the most promising layer 2 solutions for Ethereum's scalability and cost issues. Discover which one suits your needs best.
March 12, 2022 12:32 PM
How to Add Binance Smart Chain to Metamask?
How to add Binance Smart Chain to Metamask? In this easy guide, we take you step by step and show you how exactly to plug Metamask to BSC.

October 13, 2018 8:10 PM
Bitcoin Influences Income Tax Court Ruling
The Supreme Court ruled that stocks cannot be charged income tax - referencing Bitcoin and cryptocurrencies with the progress of how we define money
August 18, 2026 7:13 AM

Bitcoin Tax Reporting in Austria 2026: What Applies
Bitcoin tax reporting in Austria: which data investors can request from crypto exchanges in 2026, and when the report matters for the tax return.
September 9, 2026 4:22 PM

Crypto Tax in Germany: What Applies in 2026 and What Is Set to Change in 2027
Crypto gains are tax-free after twelve months; before that your personal tax rate of up to 45 percent applies. What triggers tax, how the holding period is calculated, what happens with staking and losses, and what the draft bill would change from 2027.
February 18, 2026 11:00 AM
Top 5 Tax Reporting Tips to Prepare for the 2026 Season
Prepare for the 2026 crypto tax season with our top 5 tips on reporting, tax-loss harvesting, and new IRS rules to avoid penalties.
October 1, 2026 7:36 PM

Crypto tax and withholding at source from 2028: what to check now
The German Federal Ministry of Finance’s draft bill goes to cabinet on October 14, 2026. The underexposed part of it is the deduction of tax from 2028: which providers are to withhold the tax on investment income, why self-custody and foreign platforms stay exempt from it, and what you should document by December 31.
August 12, 2026 6:24 PM

Tokenized Stocks and Tax in Germany: When the One-Year Holding Period Applies and When the Flat Tax Bites
If you buy a tokenized stock, you often apply the crypto rule: hold for a year, then the gain is tax-free. For these products that assumption usually does not hold, and this article shows from the wording of the law which feature decides the tax regime and how to find it in the issuer documents.
July 30, 2026 11:54 AM
Bitcoin and Ethereum Beat Every Major Market in July as Chip Stocks Crash
Crypto quietly won July. Ethereum gained 20% and Bitcoin 9%, while chip stocks fell 22% and the Nasdaq 100 slid 9%. Here is what actually happened.
August 27, 2026 7:21 AM

Crypto Gains 2026: Why the September 10 Advance Tax Payment Decides Your Interest Bill
The third income tax advance payment falls due on September 10, yet for most crypto investors none was ever set. We checked four provisions in full text and show when the interest period for 2026 starts and how you can shrink it yourself.
April 19, 2026 11:46 AM
Top 5 High-Cap Altcoins Outperforming the Market in 2026
Here are the top 5 cryptocurrencies with market caps over $1 billion leading the 2026 market. Do you own any in your crypto portfolio?
January 1, 2026 3:12 PM
Crypto Taxes 2026 in Germany: Automatic Reporting Under DAC8, What Applies Now
Since 1 January 2026 crypto providers in the EU must record their customers' transactions for the tax authorities. The first report for 2026 follows in 2027. What investors need to know.

July 31, 2026 10:59 AM

German Crypto Tax Return 2025: What You Should Know Now the July 31 Deadline Has Passed
Recap as of September 27, 2026: the deadline for the 2025 German tax return ended on July 31, 2026 at midnight. This article describes the situation on the day of the deadline: what crypto investors had to report and what happens if the deadline is missed.
More from CryptoTicker